Is It Worth Getting Umbrella Insurance If I Own a Waterfront Home in Beaufort, SC?
Quick Answer:
Yes, umbrella insurance is often worth considering for waterfront homeowners in Beaufort, SC. Waterfront properties frequently come with additional liability exposures such as docks, boats, water access, and guest activity that can increase the risk of a lawsuit. An umbrella policy can provide an extra layer of liability protection beyond the limits of your homeowners, auto, and other eligible policies.
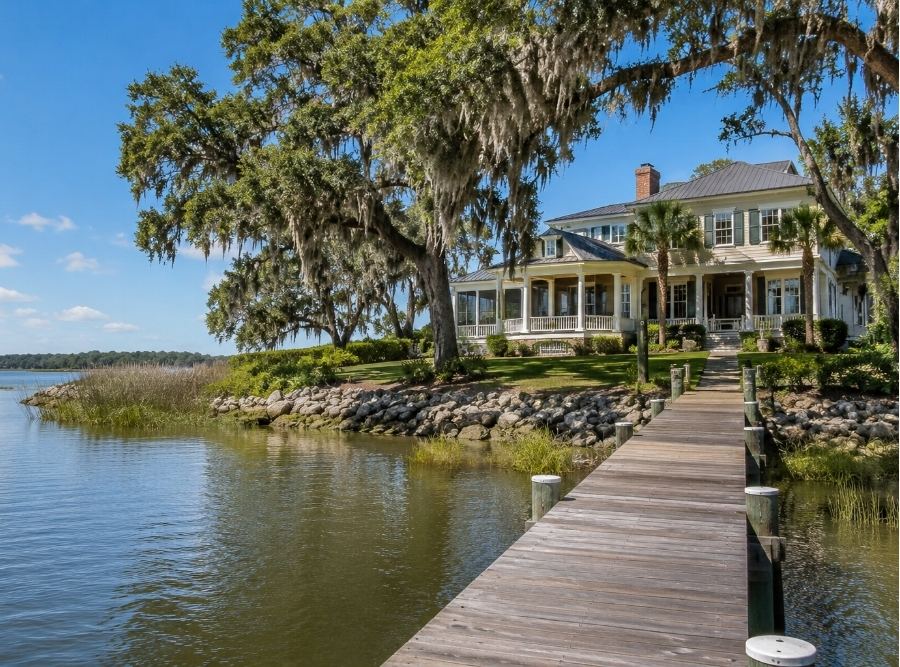
Owning a waterfront home in Beaufort comes with undeniable advantages. Whether it’s watching the sunrise over Battery Creek, enjoying weekends on the Beaufort River, or spending time with family on a private dock, waterfront living is one of the reasons many people choose to call the South Carolina Lowcountry home. What many homeowners don’t realize, however, is that waterfront properties often come with a different level of liability exposure than a typical residential property.
Most conversations about waterfront insurance focus on hurricanes, flooding, wind damage, and property protection. Those are important considerations, but they are only part of the picture. For many waterfront homeowners, the greater long-term financial risk may come from liability exposure. That’s where umbrella insurance often enters the conversation.
Why Waterfront Homes Create Different Liability Risks
Waterfront properties naturally attract activity. Friends visit, family gatherings take place, grandchildren spend time near the water, and guests often use docks, walkways, kayaks, boats, or other recreational features. While most of these experiences are enjoyable and uneventful, each one creates opportunities for accidents that simply don’t exist at many inland properties.
A wet dock, an aging walkway, a boating incident, or an injury involving a guest can quickly turn into a liability claim. Even homeowners who are diligent about maintaining their property can face situations where an accident leads to significant medical expenses, legal costs, or allegations of negligence. The reality is that lawsuits often arise not because someone intended harm, but because a serious injury occurred and someone is looking for compensation.
This is particularly relevant in Beaufort communities such as Lady’s Island, Habersham, Battery Point, The Point, and other waterfront areas where private docks, boat lifts, and direct water access are common. The more ways people interact with your property, the more important it becomes to evaluate whether your liability protection is keeping pace with your actual exposure.
The Coverage Gap Many Homeowners Never See Coming
One of the most common misconceptions we encounter is the belief that a homeowners policy automatically provides enough liability protection for any situation. While homeowners insurance includes personal liability coverage, those limits are often much lower than many homeowners realize.
A serious injury claim can escalate quickly. Medical treatment, rehabilitation, lost wages, legal expenses, and potential settlements can push the cost of a claim well beyond standard liability limits. When that happens, the homeowner may become personally responsible for amounts that exceed the protection provided by the underlying policy.
The issue becomes even more significant as property values and personal assets increase. Many waterfront homeowners purchased their property years ago when home values were considerably lower. Over time, assets may have grown, retirement accounts may have increased, and overall net worth may be substantially higher than it was when the insurance policy was originally purchased. Unfortunately, liability limits often remain unchanged for years unless someone intentionally reviews them.
This is where homeowners frequently get caught off guard. They spend considerable time protecting their home, boat, and investments, yet rarely revisit the liability coverage designed to protect those assets if a major lawsuit occurs.
What Most Waterfront Homeowners Don’t Realize About Umbrella Insurance
The question most people ask is whether they have enough homeowners insurance. The question they should be asking is whether their liability exposure has outgrown their liability limits.
We’ve seen homeowners focus almost entirely on property-related risks while overlooking how dramatically liability exposure can increase after purchasing a waterfront home. The addition of a dock, boat, golf cart, personal watercraft, or even frequent entertaining can create exposures that didn’t exist previously. In many cases, the homeowner’s lifestyle changes far more than their insurance coverage does.
Another misconception is that umbrella insurance is only for the extremely wealthy. In reality, umbrella coverage is often valuable for homeowners who have accumulated assets over time, own waterfront property, host guests regularly, have teenage drivers, own boats, or simply want an additional layer of protection against catastrophic claims. The purpose is not to protect only what you have today. It is also designed to help protect future earnings, retirement planning, and long-term financial goals from being disrupted by a significant liability claim.
The homeowners who benefit most from umbrella insurance are often not those who expect to be sued. They are the ones who recognize that unexpected accidents can happen despite their best efforts to prevent them.
Why Boat Owners Should Pay Close Attention
For many Beaufort waterfront homeowners, the conversation doesn’t stop at the house itself. Boat ownership introduces another layer of liability exposure that deserves careful consideration. A boating accident involving injuries can lead to claims that extend far beyond property damage. Depending on the circumstances, medical expenses, legal costs, and potential settlements can become substantial.
Many homeowners assume their boat policy alone provides all the protection they need. While boat insurance plays an important role, it’s important to understand how liability coverage works across all policies. A coordinated insurance strategy often includes homeowners coverage, auto insurance, boat insurance, and an umbrella policy working together to create broader protection.
We’ve seen situations where homeowners were comfortable with their property coverage but had never evaluated how a significant boating liability claim could affect their broader financial picture. That’s why waterfront homeowners often benefit from looking at their overall liability exposure rather than evaluating each policy in isolation.
Why an Independent Insurance Review Matters
Insurance decisions become more complex as life changes. Purchasing a waterfront home, building a dock, buying a boat, entering retirement, or accumulating assets can all affect liability needs. Unfortunately, many policies remain largely unchanged even as a homeowner’s circumstances evolve.
At Coastal Haven Insurance, we believe umbrella insurance should never be treated as a one-size-fits-all recommendation. The right amount of liability protection depends on the property, lifestyle, assets, future plans, and overall risk profile of the homeowner. What makes sense for one waterfront property owner may be very different from what makes sense for another.
As an independent agency, we work with homeowners to evaluate liability exposure from a broader perspective rather than focusing solely on policy limits. Our goal is not to sell more insurance. Our goal is to help clients understand where vulnerabilities may exist and determine whether additional protection is appropriate for their situation.
The Real Question Isn’t Cost—It’s Exposure
Many homeowners begin by asking whether umbrella insurance is worth the premium. A better question is whether the potential financial consequences of a major liability claim justify having additional protection in place. For waterfront homeowners in Beaufort, the answer often depends on far more than the value of the home itself.
Waterfront living brings unique opportunities, but it also brings unique responsibilities. Docks, boats, guests, recreational activities, and growing personal assets can all contribute to liability exposure that may not be fully addressed by standard policy limits alone. The goal of umbrella insurance isn’t to assume the worst will happen. It’s to make sure one unexpected event doesn’t jeopardize everything you’ve worked hard to build.
If you own a waterfront home in Beaufort, Lady’s Island, Port Royal, Habersham, or elsewhere in the South Carolina Lowcountry, reviewing your liability coverage may be one of the most important insurance conversations you have. Understanding your exposure today can help you make more informed decisions before a claim ever occurs.
Coastal Haven Insurance Partners is an independent, locally owned insurance agency located in Bluffton, SC (40 Pennington Dr Suite E). Led by partners Coley Davis, Travers Davis, and William Voelkel, the firm brings over 30 years of combined insurance and leadership experience to the South Carolina Lowcountry. The team specializes in tailored homeowners, flood, windstorm, auto, and commercial insurance. They share straightforward guidance to help coastal residents and business owners protect their assets with confidence.